Emmvee Photovoltaic Power Q2 FY27 Results: Consolidated Net Profit ₹382 Crore on Total Income of ₹1,579 Crore
Earnings
Renewable Energy
Blacklitt Research3 min read
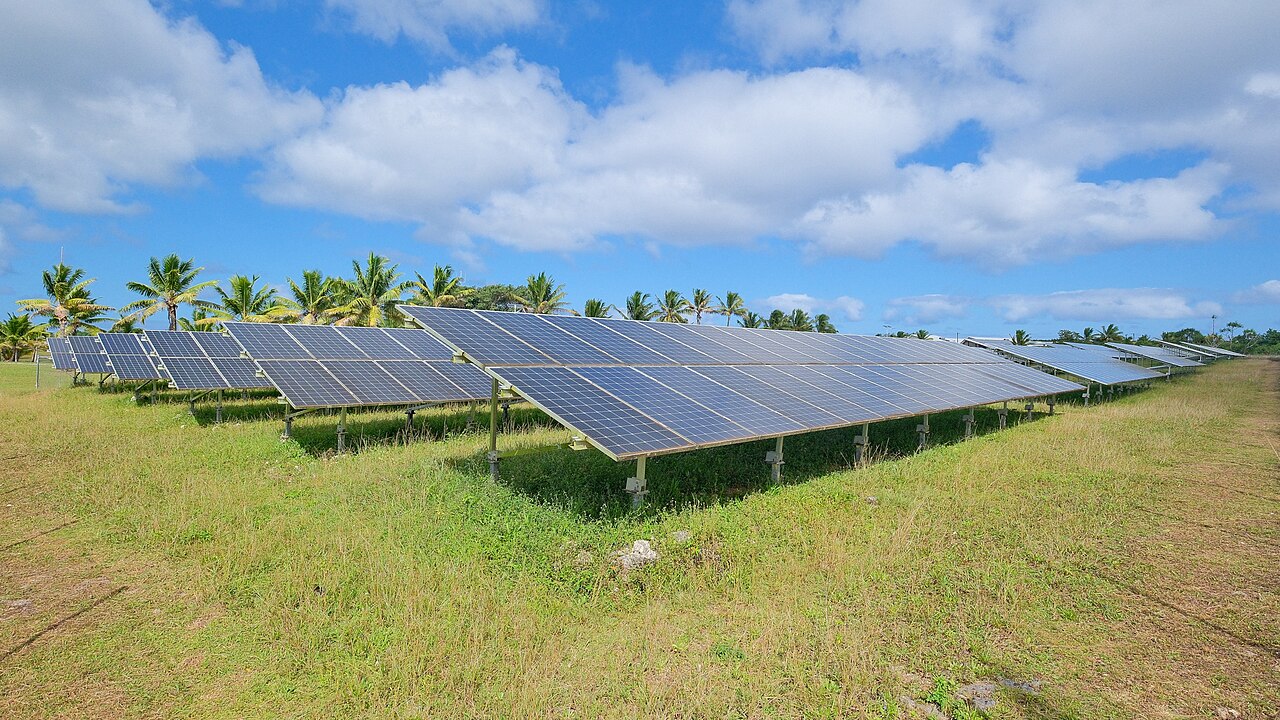
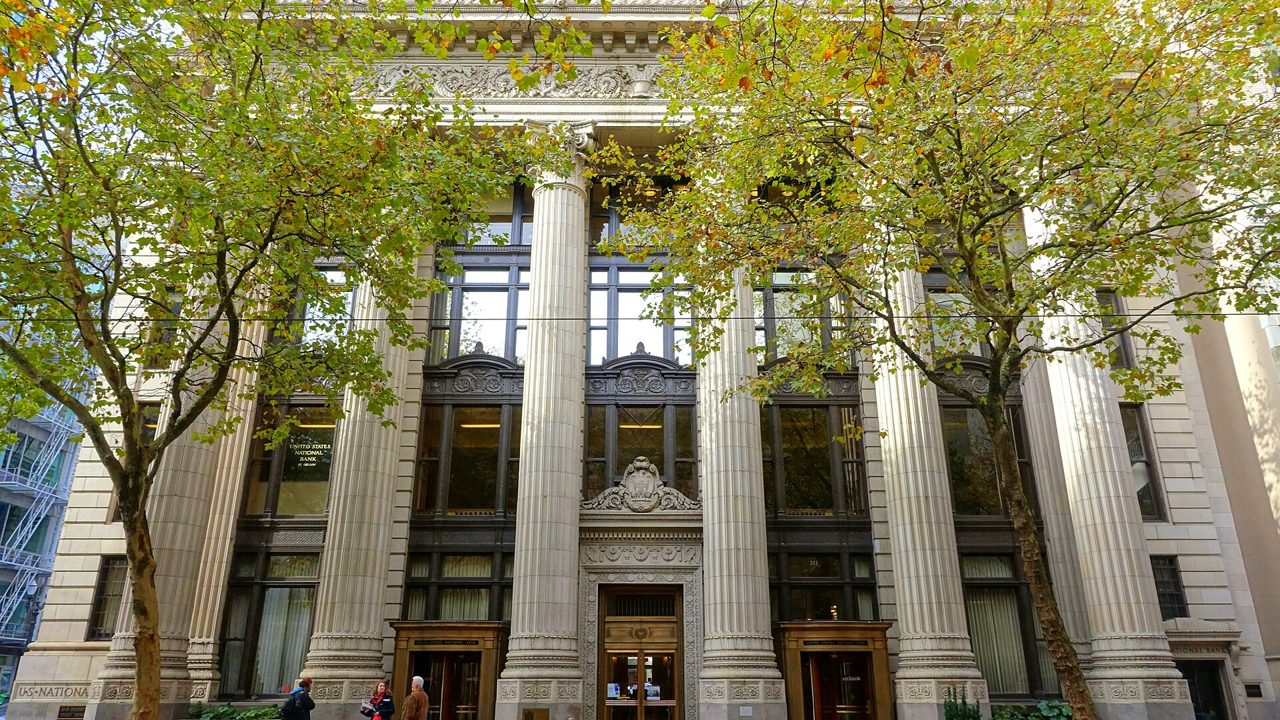
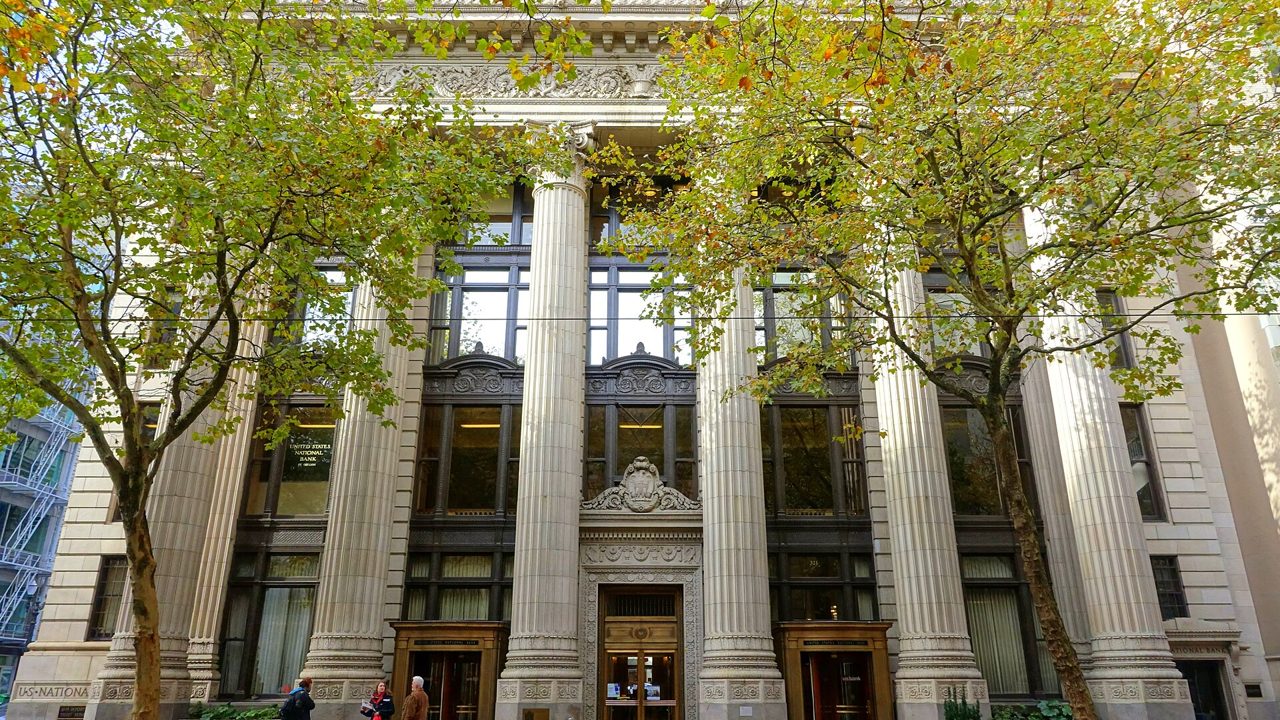
Illustrative image. Photo: Pseudopanax, via Wikimedia Commons (public domain)
Emmvee Photovoltaic Power reported consolidated total income of ₹1,578.89 crore and net profit of ₹382.05 crore for the quarter ended 30 Sep 2026. Standalone total income was ₹257.79 crore and net profit was ₹6.87 crore.
Key highlights
Consolidated
Including its subsidiaries
Total income: ₹1,579 crore, up 37.4% YoY, up 0.4% QoQ
Net profit: ₹382 crore, up 60.6% YoY, up 0.5% QoQ
EPS: ₹5.52, against ₹4.01 in Q2 FY26
Finance costs: ₹9.47 crore, down 82.9% YoY from ₹55.25 crore
Standalone
The company on its own, without its subsidiaries
Total income: ₹258 crore, down 12.5% YoY, down 4.2% QoQ
Net profit: ₹6.87 crore, down 68.8% YoY, down 81.4% QoQ
EPS: ₹0.10, against ₹0.37 in Q2 FY26
Net profit: ₹6.87 crore, down 81.4% QoQ from ₹36.87 crore
Summary
Consolidated ₹ crore
Particulars
Q2 FY27
Q2 FY26
YoY
Q1 FY27
QoQ
1,578.89
1,149.39
+37.4%
1,571.99
+0.4%
Revenue from operations
1,576.37
1,131.00
+39.4%
1,555.51
+1.3%
Other income
2.52
18.39
-86.3%
16.48
-84.7%
382.05
237.86
+60.6%
380.29
+0.5%
Finance costs
9.47
55.25
-82.9%
11.08
-14.5%
Depreciation
84.63
70.87
+19.4%
83.90
+0.9%
Tax expense
83.25
53.81
+54.7%
89.32
-6.8%
Net profit margin
24.20%
20.69%
+3.50 pp
24.19%
+0.01 pp
Tax as share of profit before tax
17.9%
18.4%
-0.56 pp
19.0%
-1.13 pp
EPS, basic (₹)
5.52
4.01
+37.7%
5.49
+0.5%
Figures are in ₹ crore; YoY compares with Q2 FY26 and QoQ with Q1 FY27. Click Total income or Net profit to see the rows behind them.
Profit grew faster than revenue, and a quarter of the gain is lower interest. Revenue from operations rose 39.4% to ₹1,576.37 crore and net profit 60.6% to ₹382.05 crore. Profit before tax rose to ₹465.3 crore from ₹291.7 crore, a ₹173.6 crore gain, of which ₹45.8 crore (26%, derived) is the fall in finance costs to ₹9.47 crore from ₹55.25 crore. EBITDA was ₹556.9 crore, a margin of 35% that is the same as a year ago, and gross margin fell to 42% from 47%, so the operating margin was held by other costs.
Against June revenue rose 1.3% and profit was level at ₹380.29 crore. For H1 FY27 revenue from operations rose 45.1% to ₹3,131.9 crore, EBITDA 47.4% to ₹1,105.0 crore and profit after tax 79.1% to ₹762.3 crore. Tax was 17.9% of profit before tax against 18.4%.
The operating figures: solar module production was 952 MW against 682 MW, and cell production 513 MW against 319 MW. Effective capacity utilisation was 89% for cells but 44% for modules, so more than half of module capacity was idle. The order book was 10.4 GW with about 1.5 GW of new inflows in the quarter, installed annual capacity was about 10.3 GW for modules and 2.94 GW for TOPCon cells, and net debt to equity was 0.12x.
The company is progressing a 6 GW integrated TOPCon module and cell expansion, taking annual capacity to about 16.3 GW of modules, and plans phased backward integration into 9 GW of ingot and wafer manufacturing, 5 GW in FY29 and 4 GW in FY30, subject to regulatory clarity on ALMM III timelines and market conditions. The estimated capital expenditure is ₹5,000-5,500 crore, to be funded largely through internal accruals.
Standalone ₹ crore
Particulars
Q2 FY27
Q2 FY26
YoY
Q1 FY27
QoQ
257.79
294.54
-12.5%
269.17
-4.2%
Revenue from operations
209.97
276.66
-24.1%
216.82
-3.2%
Other income
47.82
17.88
+167.4%
52.35
-8.7%
6.87
22.01
-68.8%
36.87
-81.4%
Finance costs
0.13
3.33
-96.1%
0.82
-84.1%
Depreciation
5.39
9.16
-41.2%
5.25
+2.7%
Tax expense
2.93
7.54
-61.1%
12.49
-76.5%
Net profit margin
2.66%
7.47%
-4.81 pp
13.70%
-11.03 pp
Tax as share of profit before tax
29.9%
25.5%
+4.38 pp
25.3%
+4.59 pp
EPS, basic (₹)
0.10
0.37
-73.0%
0.53
-81.1%
Figures are in ₹ crore; YoY compares with Q2 FY26 and QoQ with Q1 FY27. Click Total income or Net profit to see the rows behind them.
The standalone company is a small part of the group. Its revenue from operations of ₹209.97 crore is about 13% of the group's (derived) and fell 24.1% from a year ago, and its net profit fell 68.8% to ₹6.87 crore, while other income of ₹47.82 crore is 18.5% of its total income (derived). Most of the group's earnings therefore arise in subsidiaries; the text read does not give the split.
Inference
Emmvee's profit rose faster than revenue because interest costs fell by about four-fifths, while its margin before interest was unchanged.
Module capacity was less than half used, and the expansion and ingot-wafer plan depend on regulatory timelines the filing says are not yet clear.
Create a free account to read the rest of this article and the analysis that follows.
By continuing you agree to our Terms and Privacy Policy, and to receive updates from Blacklitt by email. You can unsubscribe anytime.
Disclaimer:
The information available on this article is provided for education and informational purposes only. It does not constitute or provide financial, investment or trading advice and should not be construed as an endorsement of any specific stock or financial strategy in any form or manner. We do not make any representations or warranties regarding the quality, reliability, or accuracy of the information provided. This website may contain links to third-party content. We are not responsible for the content or accuracy of these external sources and do not endorse or verify the information provided by third parties. We are not liable for any decisions made or actions taken based on the information provided on this website.


 EMMVEEEmmvee Photovoltaic Power Ltd