Karur Vysya Bank Q2 FY27 Results: Net Profit ₹788 Crore on Net Interest Income of ₹1,497 Crore
Earnings
Banking
Blacklitt Research3 min read
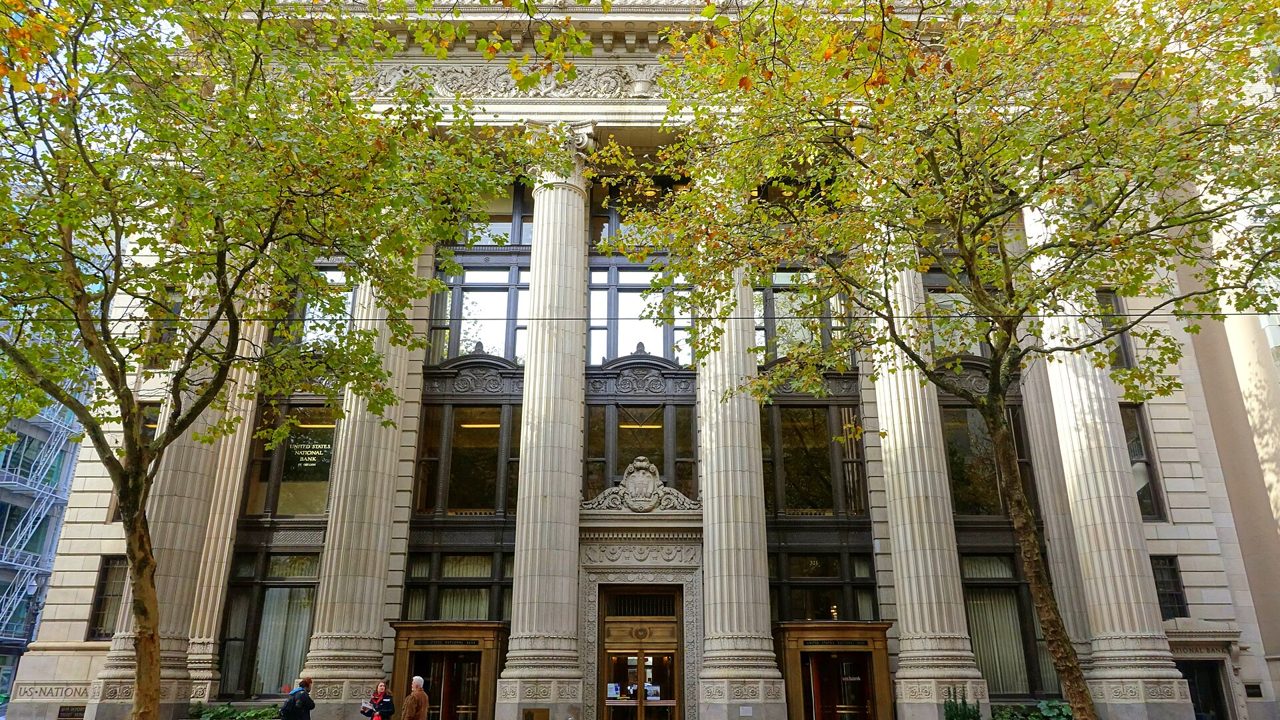
Daderot, via Wikimedia Commons (CC0 1.0). Illustrative image.
Karur Vysya Bank reported total income of ₹3,670 crore and net profit of ₹788 crore for the quarter ended 30 Sep 2026, against ₹574 crore a year earlier.
Key highlights
Standalone
The company on its own, without its subsidiaries
Total income: ₹3,670 crore, up 5.1% QoQ; the year-earlier figure is not in the filing
Net profit: ₹788 crore, up 37.3% YoY and 4.2% QoQ
EPS: ₹8.15, against ₹7.82 in Q1 FY27
Net interest income: ₹1,497 crore, up 18.7% YoY and 5.2% QoQ
Summary
Standalone ₹ crore
Particulars
Q2 FY27
Q2 FY26
YoY
Q1 FY27
QoQ
Total income
3,670
n/a
n/a
3,491
+5.1%
1,497
1,261
+18.7%
1,423
+5.2%
Commission and fee income
290
253
+14.6%
271
+7.0%
1,162
1,017
+14.3%
1,096
+6.0%
Operating expenses
770
756
+1.9%
769
+0.1%
Net profit
788
574
+37.3%
756
+4.2%
EPS, basic (₹)
8.15
n/a
n/a
7.82
+4.2%
Figures are in ₹ crore; YoY compares with Q2 FY26 and QoQ with Q1 FY27. Click Total income or Net profit to see the rows behind them.
Profit grew faster than operating profit because less of that profit went to provisions and tax. Pre-provision operating profit rose 14.3% to ₹1,162 crore, but net profit rose 37.3% to ₹788 crore, and the gap between the two, which holds provisions and tax, narrowed to ₹374 crore from ₹443 crore a year earlier (derived). The release does not give provisions or tax, so the split is not known. The bank calls the profit its highest ever.
The quarter's income is mostly interest. Net interest income of ₹1,497 crore is about 77% of operating income of ₹1,932 crore (operating profit plus operating expenses, derived), against about 71% a year ago, while commission and fee income of ₹290 crore rose 14.6%. Operating expenses grew 1.9% to ₹770 crore, and the cost-to-income ratio fell to 39.85% from 42.63%. In the table, the Q1 FY27 figures for net interest income, fees, operating profit and expenses are the half-year figure less the quarter's, because the release gives only half-year totals for them (derived); total income, net profit and earnings per share come from the stored results, which do not hold the year-earlier quarter.
The margin edged up as funding got cheaper faster than lending. The net interest margin was 4.34% against 4.24%, the cost of deposits fell 11 basis points to 5.49% and the yield on advances fell 18 basis points to 10.20%. The 28 basis point gain in the highlights compares the half year (4.34% against 4.06%).
The balance sheet is growing faster on the loan side. Advances rose 20.35% to ₹1,11,589 crore and deposits 15.96% to ₹1,28,123 crore, so advances are about 87% of deposits against about 84% a year ago (derived). Risk-weighted assets rose about 21% to ₹87,496 crore (derived), faster than advances. The CASA ratio is 27.52%, total business is ₹2,39,712 crore (+17.96%) and the balance sheet ₹1,50,831 crore (+15.94%).
Asset quality ratios are low, but the amount of bad loans rose. Gross NPA was 0.69% of gross advances (₹765 crore) against 0.76% (₹708 crore) a year ago, so the amount is about 8% higher while the ratio is lower because advances grew faster (derived). Net NPA was 0.18%. Return on assets was 2.10% and return on equity 20.47% for the quarter.
The release is not consistent on capital. Its highlights give a capital adequacy ratio of 18.61% with a Common Equity Tier 1 ratio of 17.98%, but the capital adequacy section gives 17.97% against a regulatory requirement of 11.50%, with Tier 1 at 17.32%, which is below the CET1 figure that the highlights quote. The release does not reconcile them, and the figures are not adopted here. It does not label the results consolidated or standalone; they are shown as standalone.
Inference
Karur Vysya's profit grew faster than its operating profit, which the release attributes to the bank's own performance without giving the provisions and tax lines behind it.
Loans are growing faster than deposits and risk-weighted assets faster than loans, and the capital ratios in the release do not agree with each other, so the capital position is better read from the full results statement.
Create a free account to read the rest of this article and the analysis that follows.
By continuing you agree to our Terms and Privacy Policy, and to receive updates from Blacklitt by email. You can unsubscribe anytime.
Disclaimer:
The information available on this article is provided for education and informational purposes only. It does not constitute or provide financial, investment or trading advice and should not be construed as an endorsement of any specific stock or financial strategy in any form or manner. We do not make any representations or warranties regarding the quality, reliability, or accuracy of the information provided. This website may contain links to third-party content. We are not responsible for the content or accuracy of these external sources and do not endorse or verify the information provided by third parties. We are not liable for any decisions made or actions taken based on the information provided on this website.


 KARURVYSYAKarur Vysya Bank Ltd