Mutual Funds vs Stocks: Key Differences for Indian Investors
Mutual funds and stocks differ mainly in who makes the decisions and how much a single mistake can cost you. A mutual fund pools your money with other investors and hands it to a professional manager, who spreads it across many companies. Buying stocks gives you full control, but each choice counts for more in your portfolio.
Comparing mutual funds vs stocks comes down to diversification, management, cost, time, tax and control.
Mutual funds vs stocks at a glance
The two approaches differ on six points.
| Feature | Mutual fund | Individual stocks |
|---|---|---|
| Who chooses the holdings | A fund manager, within the fund's stated mandate | You |
| Diversification | Usually spread across many companies in one purchase | Depends on how many shares you buy |
| Management and time | Handled by the fund manager; you pick the fund | Research and monitoring fall on you |
| Cost | A yearly expense ratio taken from the fund's assets | Brokerage and transaction charges on each trade |
| Tax | Capital gains tax when units are sold | Capital gains tax when shares are sold |
| Control | Choice of fund, plan, and when to buy or sell units | Choice of every company, price and sale |
Tax rules as of October 2026.
Diversification: one fall reaches your money differently
Diversification means a fall in one holding touches only part of your money. A fund that holds many companies spreads that risk across them, while a concentrated stock portfolio puts it on a few names. The example below uses the same ₹6 lakh held three ways.
A 40% fall in one holding
Suppose one holding falls 40% and every other holding stays unchanged. The table compares three ways to hold ₹6 lakh.
| Measure | 30 holdings | 10 holdings | 1 holding |
|---|---|---|---|
| Amount in the fallen holding (₹) | 20,000 | 60,000 | 6,00,000 |
| Loss on the fallen holding (₹) | 8,000 | 24,000 | 2,40,000 |
| Fall in total portfolio (%) | 1.33 | 4.00 | 40.00 |
Hypothetical figures. Holdings are equal in amount.
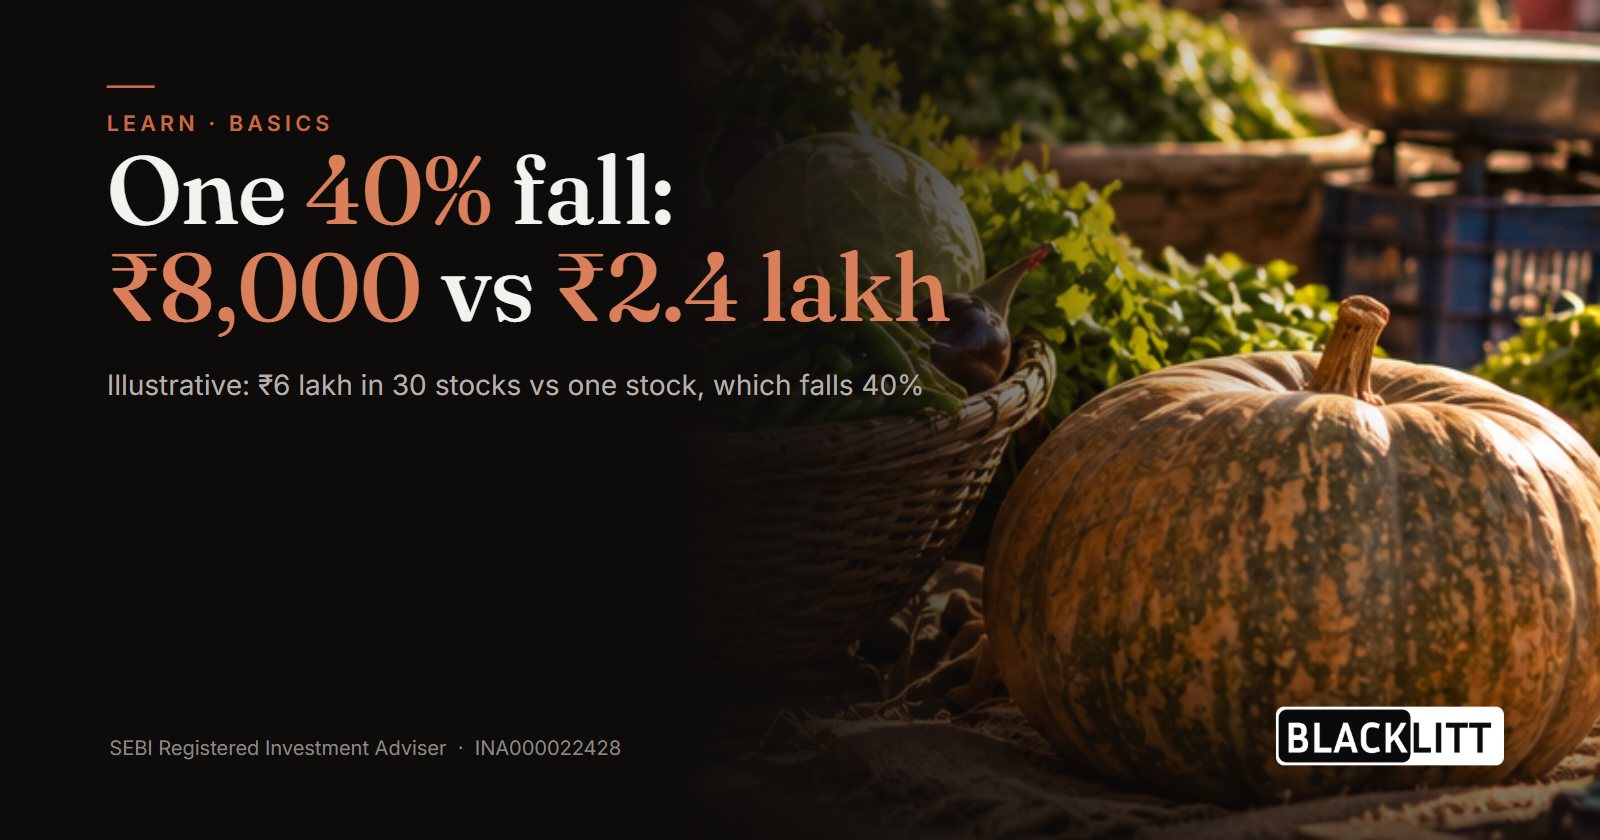
With 30 equal holdings of ₹20,000, the fall costs ₹8,000, or 1.33% of the portfolio. Put the entire ₹6 lakh in that one stock and the same 40% fall costs ₹2.4 lakh, leaving ₹3.6 lakh. Even 10 holdings would lose ₹24,000, or 4%. Real holdings tend to move together, so the gap is usually narrower than this in practice, but the direction holds: fewer holdings means one company can shape your total value.
Management and the time it takes
A mutual fund has a professional manager who researches companies, decides what to buy and sell, and rebalances within the fund's mandate. Your task is to pick a fund that fits your goal and to stay with it.
Stocks put that work on you. You research each business, decide when to buy, and decide when to sell. A few holdings are manageable for a part-time investor, but the effort grows quickly as the list lengthens. Funds trade that effort for a yearly cost, which leads to the next point.
Cost: ongoing fees compared
A mutual fund charges an expense ratio, a yearly fee deducted from the fund's assets, so the charge is paid through the fund's value rather than as a separate bill. Stocks carry brokerage and transaction charges on each buy and sell. An investor who trades rarely pays those charges only on the few trades made, while a fund investor pays the expense ratio every year.
As a hypothetical, take a yearly cost of 1% on ₹5 lakh. That is ₹5,000 a year, or ₹50,000 over 10 years if the amount does not grow. The same arithmetic applies to any ongoing charge, so compare the expense ratio before you invest, as explained in the guide to expense ratios.
Tax: the equity rules are similar for both
As of October 2026, gains on equity mutual fund units are taxed when you sell. Gains on units held for 12 months or less are short-term and taxed at 20%. Gains on units held for more than 12 months are long-term and taxed at 12.5% above ₹1.25 lakh in a financial year. Both rates carry 4% cess added. These rates apply to transfers on or after 23 July 2024 and to units on which securities transaction tax (STT) is paid. Surcharge is ignored here.
Take a ₹3 lakh gain in a year with no other gains. This example applies the same equity rates to shares, to keep the comparison simple.
| Measure | Long-term (over 12 months) | Short-term (12 months or less) |
|---|---|---|
| Rate before 4% cess (%) | 12.5 | 20.0 |
| Gain (₹ lakh) | 3.00 | 3.00 |
| Exempt amount (₹ lakh) | 1.25 | — |
| Taxable gain (₹ lakh) | 1.75 | 3.00 |
| Tax including cess (₹ lakh) | 0.23 | 0.62 |
Hypothetical gain. Rates as of October 2026.
The tax bill for the same gain depends on how long you held, not on whether the holding was a fund or a share. Holding past 12 months changes the rate, so timing matters more than the wrapper. For the full set of rules, see the guide to equity fund taxation.
Control: what you can choose
With a mutual fund, you choose the fund, the plan and when to buy or sell units. You do not choose the individual companies it holds. With stocks, you choose every company, every price and every sale.
That control has a price in attention. Each decision you take on yourself is one you can get wrong, and you carry the consequences alone. A fund shifts those decisions to a manager, but you give up the power to act on your own view of a particular company.
Choosing between a mutual fund and direct equity
A mutual fund suits you if you want a professional to spread and manage the holdings, you have little time for research, or you are just starting. An index fund is one low-effort option for the core, as explained in the guide to index funds.
Stocks suit you if you enjoy research, can follow companies closely, and accept that one holding can move your total value sharply. Some investors combine the two: funds for the broad core, and a smaller stock portion they can afford to see move a lot. If the structure of a fund is new to you, start with what a mutual fund is.
Frequently asked questions
Is a mutual fund better than stocks?
Neither is better for every investor. A mutual fund suits someone who wants a professional to choose and spread the holdings. Stocks suit someone who wants full control and has the time to research companies. Many investors combine the two, with the mix set by the time and attention they can give.
Can a mutual fund lose money when the market falls?
Yes. A mutual fund holds shares, so its value moves with the market. Diversification limits the damage from any single company, but it does not protect the value when the whole market falls. Expect the value to swing along the way, and plan to hold for the long term.
Which costs more over time, a mutual fund or stocks?
It depends on how you invest. A fund charges an expense ratio every year, taken from its assets. Stocks charge brokerage and transaction costs on each trade, so an investor who trades often can pay more than a fund investor. A long-term holder who trades rarely may pay less than the fund's yearly charge.
Disclaimer
This article reflects the author's views as of 11 November 2026. Past performance does not indicate future returns. Examples that use assumed returns are for illustration only and are not projections. Consider your own goals and risk profile before investing.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
The securities quoted are for illustration only and are not recommendatory.
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Blacklitt Technologies Private Limited · SEBI RIA INA000022428 · BSE enlistment 2491