What Is a Mutual Fund? A Plain-English Guide for Indians
- Basics
A mutual fund pools money from many investors and invests it in shares, bonds or other assets, according to a stated objective. A professional fund manager makes the buying and selling decisions, and each investor owns units in proportion to the money put in. Units are priced once a day at the scheme's NAV.
This guide explains what is mutual fund in plain words, how the money is run, the main fund types, lump sum against SIP, costs and risks. Facts are as of October 2026.
Pooled money and shared ownership
A mutual fund is a collective investment. Your money joins everyone else's, so a fund can hold many shares or bonds with a modest amount from each investor. Ownership is recorded in units, not in individual shares.
Units and NAV in plain terms
The NAV, or net asset value, is the price of one unit on a given day. When you invest, you receive units equal to the amount invested divided by that day's NAV. Your holding's value is your units multiplied by the latest NAV, so a rising NAV raises your value without changing the number of units you own.
Three parties with separate jobs
The asset management company (AMC) is the fund house. It sets up the scheme, employs the fund managers and runs the investments. The trustee is a separate board that holds the fund's assets for investors and checks that the AMC follows the rules. SEBI, the Securities and Exchange Board of India, is the regulator that sets the rules on categories, disclosures and costs. In short, the AMC manages, the trustee oversees, and SEBI regulates.
Five families of mutual funds
Funds fall into a few broad families, and SEBI sets category rules within them. For example, a flexi cap fund must hold at least 65% in equities as of October 2026, while the equity share of a hybrid fund is set by its category range.
| Family | What it invests in | Typical role | Main risk |
|---|---|---|---|
| Equity funds | Shares of listed companies, across large, mid or small companies | Long-term growth | Prices can fall sharply in a weak market |
| Debt funds | Bonds, government securities and money-market instruments | Steadier, income-oriented holdings | Interest-rate and credit risk |
| Hybrid funds | A mix of equity and debt, within a set range | A blend in one fund | Depends on the mix; falls when equities fall |
| Index and ETF funds | Track a benchmark index such as the Nifty 50; ETFs trade on the stock exchange | Low-cost market exposure | Falls with the index; small tracking differences |
| Fund of funds | Units of other mutual funds, including overseas funds | One holding across several schemes or markets | Two layers of costs; currency moves on overseas holdings |
A category shows a fund's mandate, not its quality. Two equity funds in one category can hold very different stocks.
Lump sum and SIP compared
A lump sum is one investment at one point in time. A systematic investment plan (SIP) puts a fixed amount in at regular intervals, usually monthly.
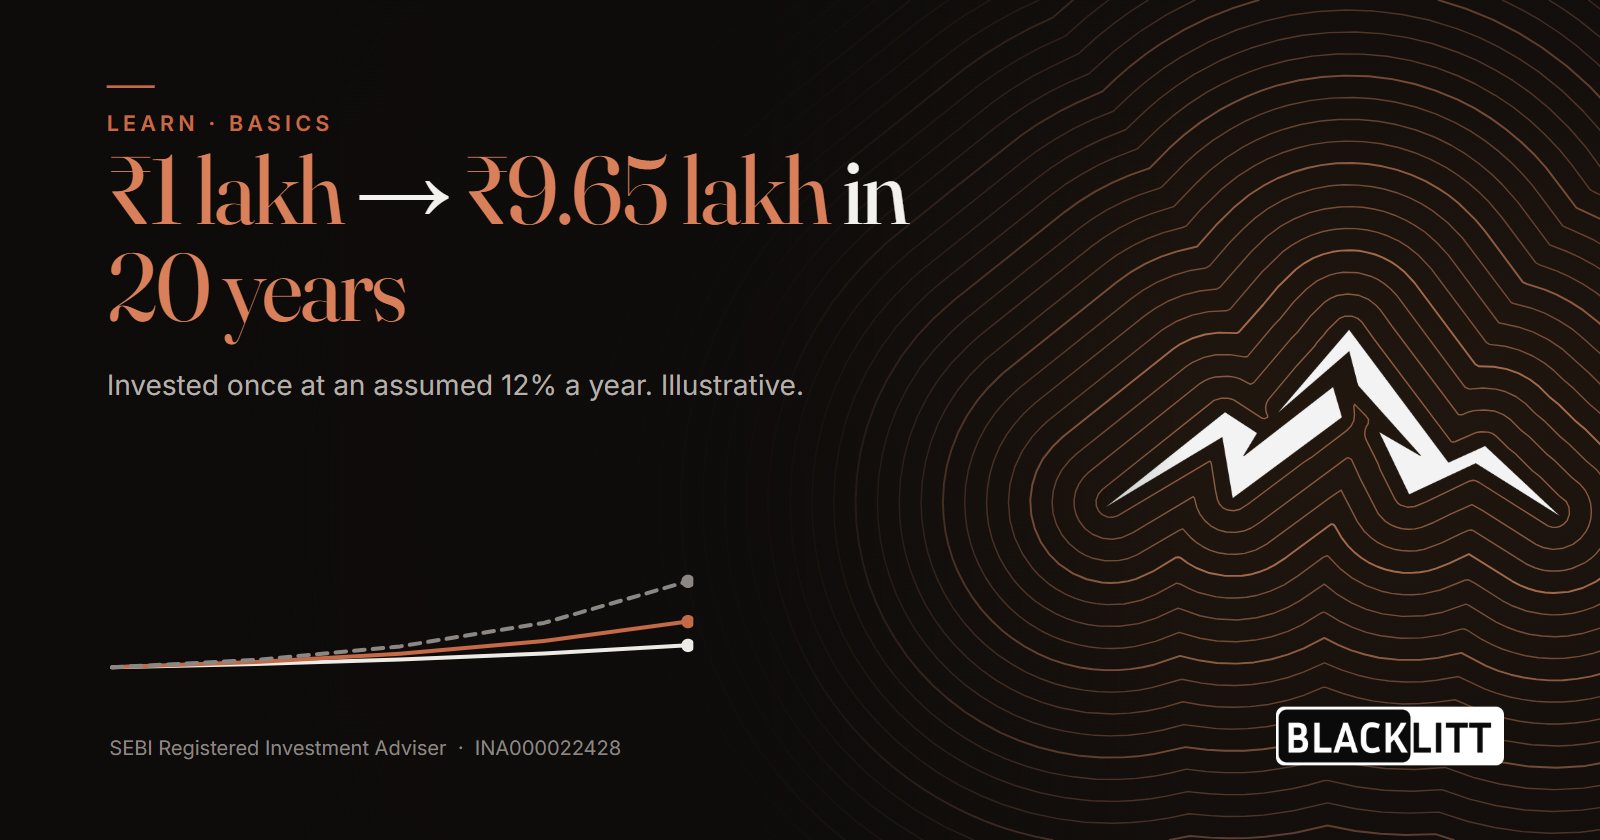
Suppose you invest ₹1 lakh once at an assumed 6%, 9% or 12% a year, with annual compounding:
| Year | 6% a year (₹ lakh) | 9% a year (₹ lakh) | 12% a year (₹ lakh) |
|---|---|---|---|
| 0 (start) | 1.00 | 1.00 | 1.00 |
| 5 | 1.34 | 1.54 | 1.76 |
| 10 | 1.79 | 2.37 | 3.11 |
| 15 | 2.40 | 3.64 | 5.47 |
| 20 | 3.21 | 5.60 | 9.65 |
Illustrative figures at assumed constant returns. Real returns vary from year to year; the lines show how compounding builds at a steady rate.
- 6% a year
- 9% a year
- 12% a year
Illustrative figures at assumed constant returns. Annual compounding.
A monthly SIP of ₹10,000 for 10 years at an assumed 12% a year puts ₹12 lakh in and grows to about ₹22.4 lakh. A SIP spreads purchases across market levels, but it does not remove the risk of a fall. Later you can raise the monthly amount with a step-up.
| Feature | Lump sum | SIP |
|---|---|---|
| How money goes in | One payment | Fixed amount at set intervals |
| Suits | Money you already have to invest | Investing from regular monthly income |
| Entry price | Set by the NAV on one day | Averaged across many dates |
| Discipline needed | Low after the purchase | Continues every month |
Costs: expense ratio and exit load
Every fund charges an expense ratio, an annual fee expressed as a percentage of assets. It is deducted from the fund's NAV, so you never see a separate bill, but it lowers your return. A lower expense ratio keeps more of the return with you, which is why cost matters most over long periods. SEBI sets ceilings on the base expense ratio, and the ceilings fall as a fund grows. The current limits sit under the SEBI (Mutual Funds) Regulations, 2026, which took effect on 1 April 2026.
Some funds also charge an exit load, a fee on units sold within a set period after purchase. The exact rate and period are in the scheme's documents, so check them before you redeem early. Tax on your gains is a separate matter, covered in how mutual funds are taxed in India.
Direct and Regular plans compared
Most schemes come in two plans: Regular and Direct. Both hold the same portfolio. A Regular plan pays a distributor's commission out of the expense ratio, while a Direct plan has no distributor and so a lower expense ratio. SEBI introduced Direct plans from 1 January 2013. A Direct plan suits investors comfortable choosing funds themselves, and a Regular plan suits those who want a distributor's help. Read more in Direct and Regular plans explained.
Risks that come with mutual funds
Market risk is the biggest one. Equity funds can fall sharply in a weak market, and small company funds usually fall further than large company funds in a bad year. Debt funds carry interest-rate risk, because bond prices fall when rates rise, and credit risk, because a borrower may fail to pay. Fund-specific risk comes from the manager's decisions: a concentrated portfolio or a change of strategy can hurt returns even when the wider market does well.
A mutual fund is not a bank deposit. Nothing about its return is fixed in advance, and it carries no deposit insurance.
Matching a fund to your goal
Start with the goal and the time frame, then pick a category, then compare funds within it. Four questions do most of the work:
- Time horizon. Money you need within a few years belongs in lower-volatility options.
- Tolerance for falls. Ask how much a fall in value you could sit through without selling.
- Cost. Compare expense ratios within the same plan type.
- Consistency. Look at returns over several periods, not one strong year.
Frequently asked questions
Is a mutual fund a good first investment for a beginner?
It can be, because one fund spreads money across many holdings and a professional manages it. Equity and hybrid funds still move up and down with markets, so money you need within a year or two belongs elsewhere. Match the category to your time horizon and to how much fall you can accept.
What is the difference between NAV and units?
NAV is the price of one unit of a mutual fund on a given day, calculated from the value of the fund's holdings after expenses. Units are the number of pieces you own. The value of your holding is your units multiplied by the latest NAV, so a rising NAV raises your value without changing your unit count.
Should I choose a Direct plan or a Regular plan?
A Direct plan has no distributor commission, so its expense ratio is lower and more of the return stays with you. A Regular plan includes a distributor's commission and may suit investors who want a distributor's help. Pick the plan that matches how you plan to invest, and compare the expense ratios of the two plans before you decide.
Disclaimer
This article reflects the author's views as of 23 October 2026. Past performance does not indicate future returns. Examples that use assumed returns are for illustration only and are not projections. Consider your own goals and risk profile before investing.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
The securities quoted are for illustration only and are not recommendatory.
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Blacklitt Technologies Private Limited · SEBI RIA INA000022428 · BSE enlistment 2491