₹5,000 Monthly SIP: What It Could Grow Into
A ₹5,000 monthly SIP can grow to about ₹36.20 lakh in 20 years at an assumed 10% a year, from ₹12.00 lakh invested. Over 25 years the same amount could reach ₹62.16 lakh at 10%, or ₹85.11 lakh at 12%, both assumed rates.
A monthly SIP turns a fixed amount into a habit, and compounding does most of the heavy lifting over time. If you are new to the idea, what a SIP is explains the mechanics. This guide shows what a ₹5,000 monthly amount could become, how a yearly step-up changes the picture and how to divide the money across goals.
Growth of ₹5,000 a month at three assumed returns
Suppose you invest ₹5,000 at the start of every month and the money earns a constant annual return. The table shows the value after 10, 15, 20 and 25 years at 8%, 10% and 12% a year. The figures ignore tax.
| Years | Amount invested (₹ lakh) | 8% a year (₹ lakh) | 10% a year (₹ lakh) | 12% a year (₹ lakh) |
|---|---|---|---|---|
| 10 | 6.00 | 9.06 | 10.07 | 11.20 |
| 15 | 9.00 | 16.99 | 20.08 | 23.80 |
| 20 | 12.00 | 28.63 | 36.20 | 45.99 |
| 25 | 15.00 | 45.74 | 62.16 | 85.11 |
Illustrative values at assumed constant returns. Figures in ₹ lakh, rounded to two decimals.
The amount invested rises in a straight line, while the value pulls ahead as the years add up. Between 10 and 15 years the invested total moves from ₹6.00 lakh to ₹9.00 lakh, and at 10% the value moves from ₹10.07 lakh to ₹20.08 lakh. For a larger monthly amount, the ₹10,000 monthly SIP guide works through the same kind of table.
- 8% a year
- 10% a year
- 12% a year
Illustrative values at assumed constant returns. Monthly SIP of ₹5,000.
The gap widens with time
At 12% the 25-year value of ₹85.11 lakh is far above the 10-year value of ₹11.20 lakh, even though the monthly amount never changed. Most of that gap comes from the later years, when each month's returns are earned on a large base built by the months before.
Stepping up the SIP each year
A step-up SIP raises the monthly amount by a fixed percentage every year. A 10% yearly step-up takes ₹5,000 in year one to ₹5,500 in year two and ₹6,050 in year three, held constant within each year. How a SIP step-up works covers the mechanics.
| 20 years | Flat ₹5,000 a month | 10% yearly step-up |
|---|---|---|
| Amount invested (₹ lakh) | 12.00 | 34.36 |
| Value at 8% a year (₹ lakh) | 28.63 | 64.65 |
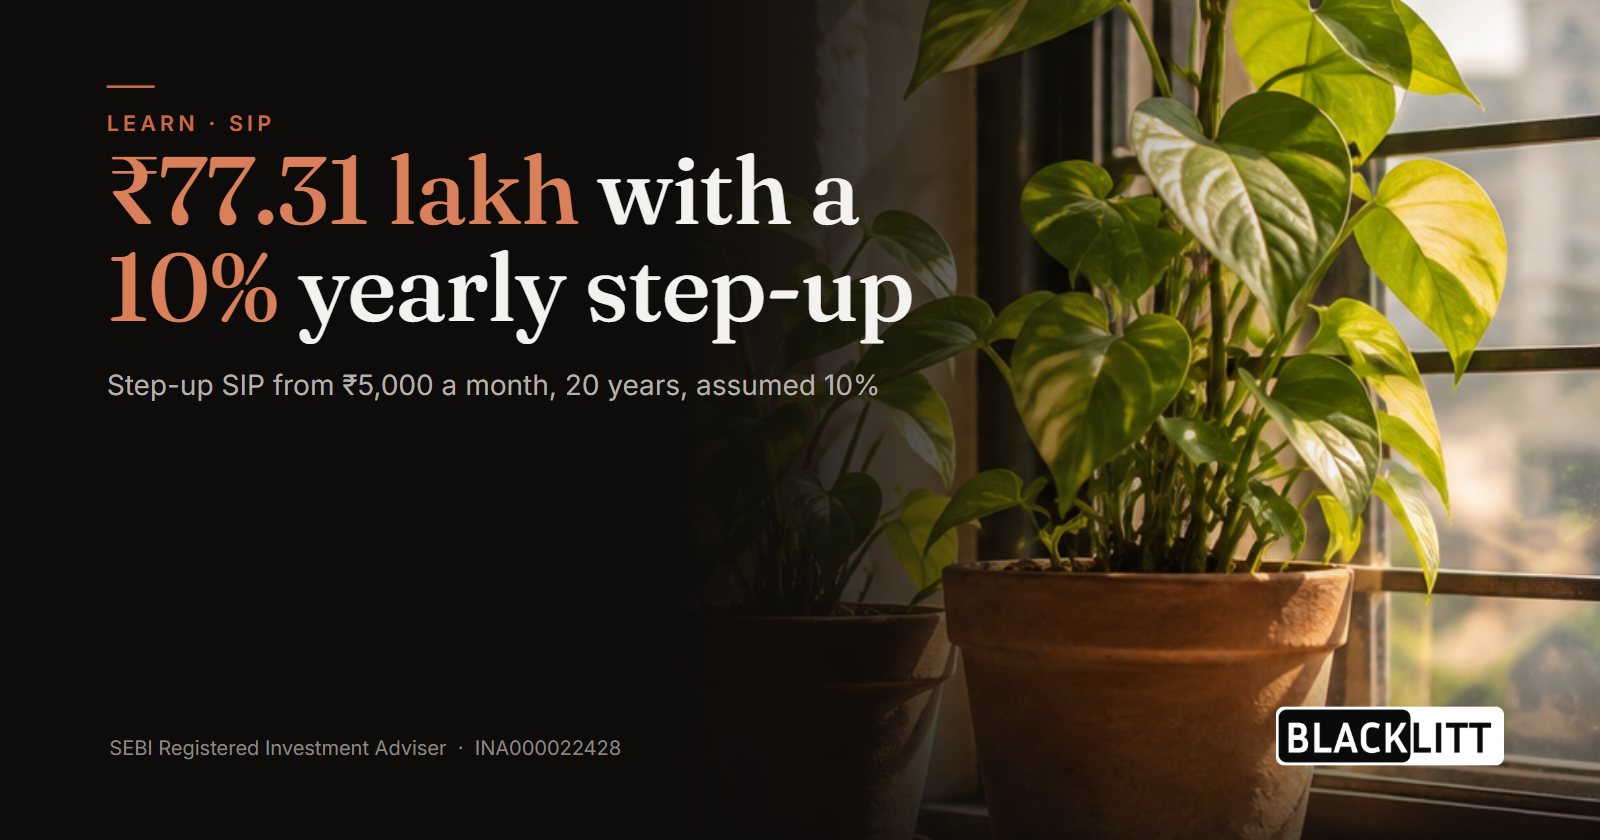
| Value at 10% a year (₹ lakh) | 36.20 | 77.31 |
| Value at 12% a year (₹ lakh) | 45.99 | 93.16 |
Illustrative values at assumed constant returns over 20 years. Figures in ₹ lakh.
At an assumed 10%, the stepped-up SIP ends near ₹77.31 lakh on ₹34.36 lakh invested. The flat ₹5,000 SIP ends near ₹36.20 lakh on ₹12.00 lakh. The step-up does more work, but it asks for a bigger commitment every year, so start at an amount you can keep paying through a slow year.
Splitting ₹5,000 across goals
Splitting the monthly amount is about purpose and time, not about choosing particular funds. Matching each part to a goal makes the plan easier to review.
| Goal | Time until the money is needed | What the holding should do |
|---|---|---|
| Expense or purchase close at hand | Short | Protect the amount first, with modest growth |
| Major goal in the medium term | Medium | Blend growth and stability, and shift gradually as the date nears |
| Long-term goal such as retirement | Long | Use growth-oriented holdings, since a long horizon leaves room to recover from falls |
Give each part a name, a target date and a review date. Costs apply to every part, so compare expense ratios before you settle on a holding.
Trade-offs of a fixed SIP plan
Equity returns do not arrive at a steady rate. A fund can rise sharply in one year and fall in the next, so a single assumed return is a planning simplification, not a forecast. Some stretches in the middle of a plan may show a value below the amount invested, and the tables above do not model them.
The 12% column is the most demanding. It needs the fund to earn that rate across the full period, which is harder than it sounds. Tax and fund costs reduce the final value, and the tables ignore both.
Frequently asked questions
How much will a ₹5,000 monthly SIP grow to in 10 years?
At an assumed 10% a year, ₹5,000 a month for 10 years grows to about ₹10.07 lakh from ₹6.00 lakh invested. At an assumed 8% the value is about ₹9.06 lakh, and at an assumed 12% about ₹11.20 lakh. These are illustrative figures that ignore tax.
Is a ₹5,000 monthly SIP enough for retirement?
It depends on how many years remain, the return a fund actually delivers and the amount you will need later. The table shows what the amount could grow to under assumptions, but it does not show how much corpus you need. Work backwards from that target and check whether the monthly amount gets you there.
Should I increase my SIP every year?
A yearly step-up can make sense when your income rises, because it lets the monthly amount keep pace with your earnings. In the 20-year illustration at an assumed 10%, a 10% yearly step-up grows to about ₹77.31 lakh from ₹34.36 lakh invested. A flat ₹5,000 a month grows to about ₹36.20 lakh from ₹12.00 lakh. The step-up needs a bigger monthly commitment.
Can I split a ₹5,000 SIP across different goals?
Many investors do, grouping money by purpose and time horizon. Money needed within a few years usually suits a different kind of holding from money for a goal ten or more years away. Give each part a clear purpose, and review the split when your goals or timelines change.
Disclaimer
This article reflects the author's views as of 8 November 2026. Past performance does not indicate future returns. Examples that use assumed returns are for illustration only and are not projections. Consider your own goals and risk profile before investing.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
The securities quoted are for illustration only and are not recommendatory.
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Blacklitt Technologies Private Limited · SEBI RIA INA000022428 · BSE enlistment 2491