How a SIP Step Up Works and Why It Matters
- SIP
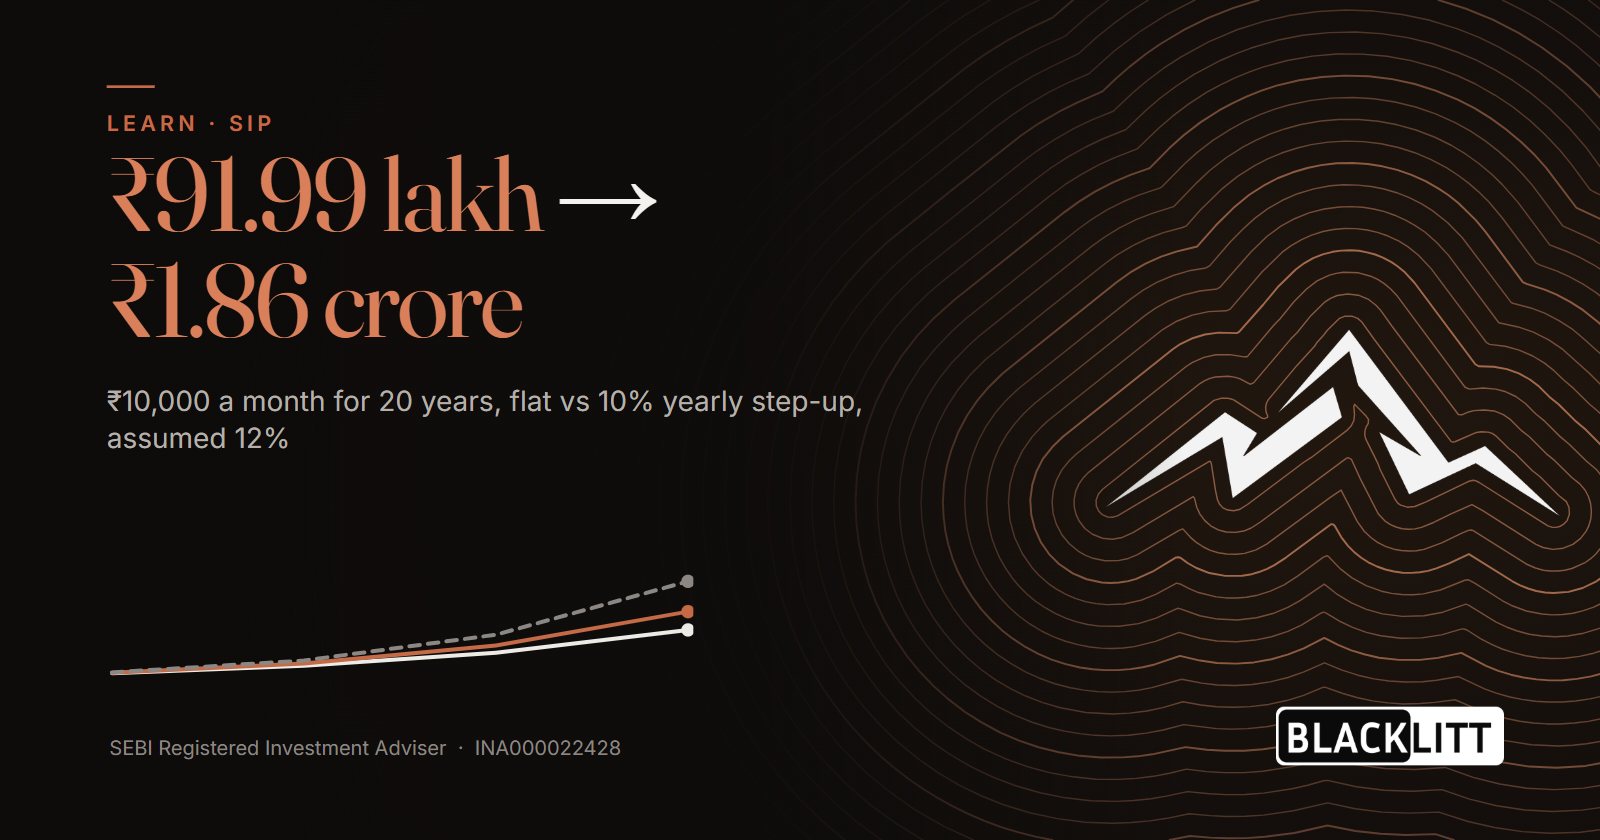
A SIP step up, also called a top-up SIP, raises your monthly SIP amount at set intervals, usually once a year, so your investing grows with your income. In the illustrations below, a 5% or 10% yearly step up lifts both the amount invested and the final value of a ₹10,000 monthly SIP.
A SIP step up explained
A systematic investment plan (SIP) buys mutual fund units at regular intervals. A step up is an instruction to raise that regular amount on a schedule. Some platforms let you add a step up to an existing SIP. Others need it set when you start. If the basic terms are new, see mutual fund basics.
Fixed amount and percentage step ups
There are two common forms. A fixed step up adds the same rupee amount each year. It suits someone with a clear savings budget that rises in set steps. A percentage step up raises the SIP by a share of the amount being paid at that time, so the rupee increase gets larger each year.
| Feature | Fixed amount step up | Percentage step up |
|---|---|---|
| How the increase is set | The same rupee amount each year | A share of the SIP in that year |
| Size of each rise | Same in rupees every year | Grows in rupees every year |
| Suits | A savings budget that rises in set amounts | Pay that rises by a fairly steady share |
| Watch for | Can become a smaller share of income over time | The rupee rise can outrun your budget |
Setting up a step up
The process differs by fund house and platform, but the steps are similar.
- Look for a step up option when you start the SIP, or in the modify option of an existing SIP.
- Choose fixed amount or percentage, the rate, and the interval. Yearly is the common interval.
- Check the auto-debit mandate limit. If it was approved for a lower amount, the higher debit can fail, so confirm the limit before the first increase.
- Confirm the date of the first increase and keep a record of it.
Before you commit, check which plan you are in. Costs differ between direct and regular plans, and that affects how much of each debit reaches the fund.
Choosing a step up rate tied to salary growth
Tie the rate to what you can save from your pay, not to a market forecast. Look at how your take-home pay has moved over the past three or four years. If your pay rises by a fairly steady share each year, a percentage step up at a similar rate keeps your savings rate roughly constant.
Many people set the rate a little below their expected pay rise, so part of each increase goes to lifestyle. The 5% and 10% cases below are examples of rates, not targets.
Step up results over 20 years
The table compares three cases of a ₹10,000 starting monthly SIP over 20 years. In the flat case the SIP never changes. The two step up cases raise it once a year.
| Case | Amount invested (₹ lakh) | Value after 20 years (₹ lakh) | Monthly SIP in year 20 (₹) |
|---|---|---|---|
| Flat ₹10,000 | 24.00 | 91.99 | 10,000 |
| 5% step up | 39.68 | 127.54 | 25,270 |
| 10% step up | 68.73 | 186.31 | 61,159 |
Illustrative figures at an assumed 12% a year, with the step up applied once a year.
- Flat ₹10,000
- 5% step up
- 10% step up
Illustrative figures at an assumed 12% a year.
The same cases at five-year intervals:
| Year | Flat ₹10,000 (₹ lakh) | 5% step up (₹ lakh) | 10% step up (₹ lakh) |
|---|---|---|---|
| Year 5 | 8.11 | 8.86 | 9.69 |
| Year 10 | 22.40 | 26.94 | 32.69 |
| Year 15 | 47.59 | 61.91 | 82.75 |
| Year 20 | 91.99 | 127.54 | 186.31 |
Illustrative figures at an assumed 12% a year. The returns are assumed, not earned. Real returns change from year to year and can be lower, so use these numbers to compare the three cases, not as a forecast.
Extra value comes mostly from investing more
The illustrations assume the same 12% a year in every case. Only the amount invested changes. So the gap in final value comes mainly from putting more money into the fund and letting that extra money compound, not from a better return. A step up does not make a fund earn more. It makes you invest more, and that is worth doing only if you can keep paying the higher SIP.
Over-committing and how to avoid it
A higher SIP is a monthly obligation. If pay falls, a job changes or a large expense arrives, a step up that was comfortable can turn into failed debits or borrowing to keep investing. Start at a level you would keep in a weak year, not in a good one. Holding a separate emergency fund also helps, because a tight month then does not force you to stop the SIP.
Pausing, reducing or stopping a step up
Most platforms let you pause a SIP, reduce it or cancel it, but the steps and notice periods differ. If you want to stop the increases but keep investing, ask the platform to switch back to a fixed amount. Stopping a SIP does not sell the units you already hold. They stay invested until you redeem them.
Frequently asked questions
Does a SIP step up increase returns?
A step up does not change the return a fund earns. It increases the amount you invest, so the final value can be higher. The illustrations here assume the same 12% a year in every case, so the extra value comes from the larger amount invested.
Can I stop a SIP step up after I start it?
Usually, yes. Most platforms let you reduce the step up, pause it or switch back to a fixed amount. The exact steps and notice periods depend on the fund house or platform, so check its SIP modify or cancel option. Stopping the increase does not sell units you already hold.
Is a percentage step up better than a fixed one?
Neither is better in every case. A percentage step up follows your pay more closely, but its rupee increase grows each year and can strain the budget. A fixed step up is easier to plan, but it can become a smaller share of your income over time. Pick the one that matches how your income moves.
What if I cannot afford the higher SIP?
Reduce the step up or pause the SIP before the debit fails, so the plan stays in order. Keeping the SIP at a level you can pay in a weak year is more useful than keeping up a rate you cannot sustain.
Disclaimer
This article reflects the author's views as of 23 October 2026. Past performance does not indicate future returns. Examples that use assumed returns are for illustration only and are not projections. Consider your own goals and risk profile before investing.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
The securities quoted are for illustration only and are not recommendatory.
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Blacklitt Technologies Private Limited · SEBI RIA INA000022428 · BSE enlistment 2491