Mutual Funds for Child Education: How to Plan
Using a mutual fund for child education means treating the goal like any other long-term target. You estimate the cost in future rupees, work out a monthly SIP that can reach it, and move part of the money into debt funds in the final years, to lower the chance that a market fall lands just before fees are due.
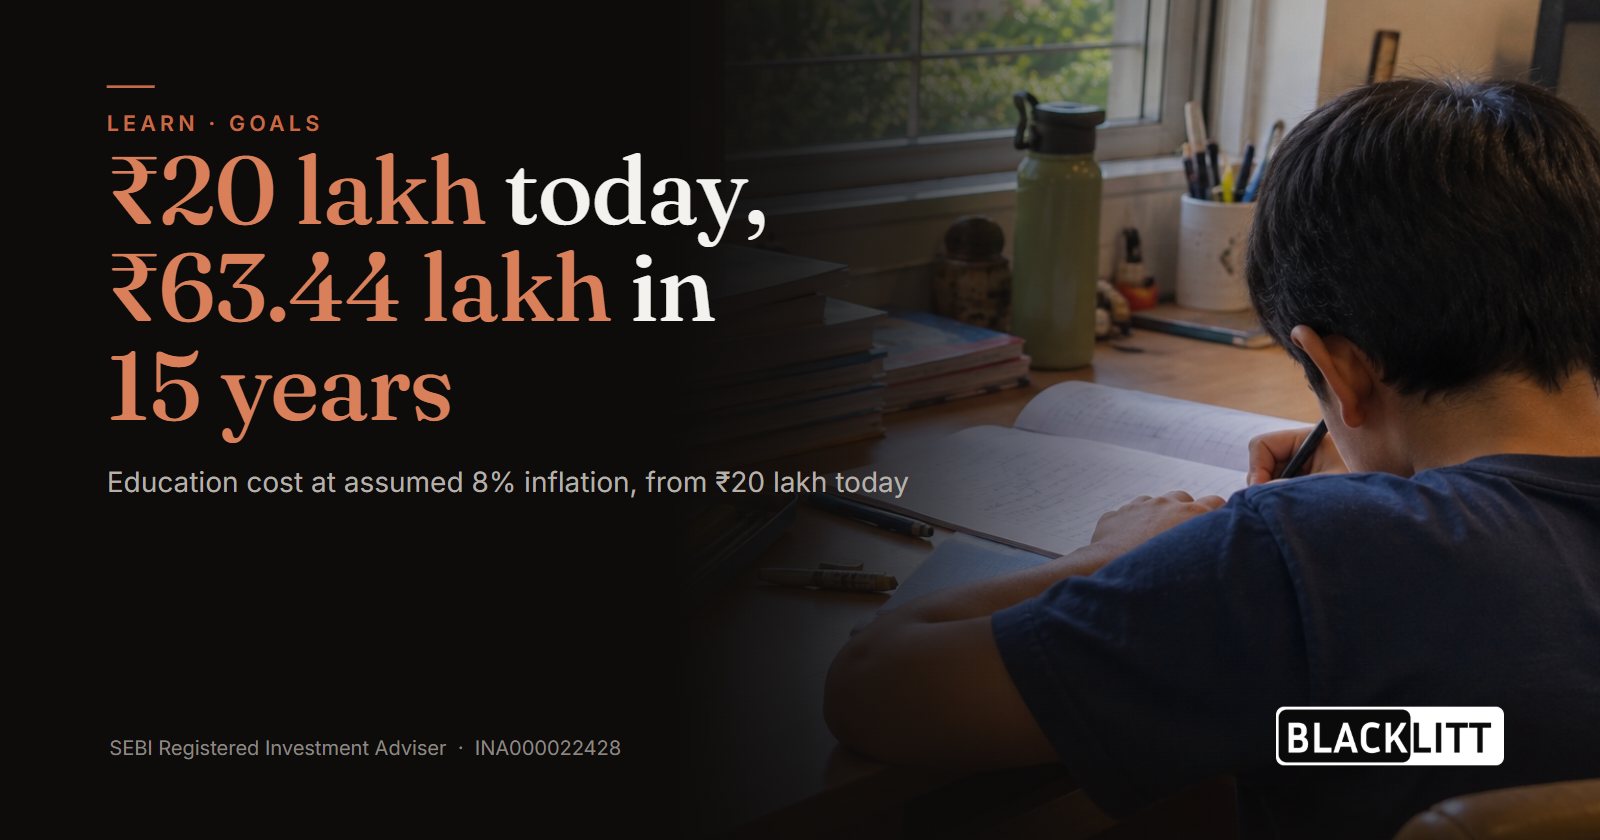
The figures here assume education costs rise 8% a year, with 10% as a higher case, and start from ₹20 lakh today. They are illustrative figures at assumed rates, not a forecast of any school or college fee.
The cost of education in future rupees
A ₹20 lakh education cost today will be higher by the time the child needs the money. The table shows how much higher at 5, 10 and 15 years.
| Years to goal | Cost at 8% inflation (₹ lakh) | Cost at 10% inflation (₹ lakh) |
|---|---|---|
| 5 | 29.39 | 32.21 |
| 10 | 43.18 | 51.87 |
| 15 | 63.44 | 83.54 |
Illustrative figures at assumed education inflation, starting from ₹20 lakh today.
The gap between the two cases is small over five years and wide over fifteen.
Monthly SIP needed for each goal
The SIP needed depends on the years left and the return the fund earns. The table shows the monthly amount for each goal at assumed returns of 10% and 12% a year.
| Years to goal | 8% inflation, 10% return (₹ a month) | 8% inflation, 12% return (₹ a month) | 10% inflation, 10% return (₹ a month) | 10% inflation, 12% return (₹ a month) |
|---|---|---|---|---|
| 5 | 38,079 | 36,233 | 41,738 | 39,715 |
| 10 | 21,433 | 19,273 | 25,750 | 23,155 |
| 15 | 15,797 | 13,330 | 20,802 | 17,554 |
Illustrative figures at assumed returns. SIP paid at the start of each month, before tax.
Illustrative figures at assumed rates. Starting cost ₹20 lakh today.
The years left matter more than the return assumption. At 8% inflation and a 12% assumed return, a 5-year goal needs ₹36,233 a month, while a 15-year goal needs ₹13,330.
Moving to debt in the final years
The reason to shift is timing. An equity fund can fall sharply close to the date fees are due, and a fall in the last year leaves little time to recover. Moving part of the money to debt in the final years trades some growth for steadier value.
The example below takes a 15-year goal with an assumed 8% education inflation, which needs ₹63.44 lakh. It compares staying in equity at an assumed 12% with a shift to debt at an assumed 6% for the last three years.
| 15-year goal, ₹63.44 lakh target | All equity at 12% | Debt in last 3 years | Difference |
|---|---|---|---|
| Monthly SIP (₹) | 13,330 | 15,612 | 2,282 |
Illustrative figures. 12% is assumed for the first 12 years. Then the whole balance and the continuing SIP earn an assumed 6% for the last three years.
The shift needs a higher monthly amount, because the last three years earn a lower assumed return. In exchange, the corpus is less exposed to a fall close to the due date. Debt funds carry their own risks. Their prices move opposite to interest rates, and a downgrade or default by a bond issuer can reduce the NAV.
Children's schemes after SEBI's 2026 change
Solution-oriented schemes, including children's schemes, were discontinued with effect from 26 February 2026. As of October 2026, new ones cannot be launched. Existing ones stopped taking fresh subscriptions immediately and are to be merged into a scheme with a similar asset allocation and risk profile, with SEBI approval.
SEBI has also created a separate Life Cycle Fund category: target-date funds with a fixed maturity year that move from equity toward debt as that date nears. Their tenure runs from 5 to 30 years in multiples of five, and they charge an exit load of 3%, 2% or 1% on exits within the first, second or third year. If you already hold a children's scheme, check with the fund house which scheme your money will move into.
Mutual fund choices for child education
Pick funds that fit the time left before the goal, the core idea behind goal-based investing. A SIP suits a fixed monthly goal, as explained in what a SIP is. Look at these public criteria:
- Cost. Direct plans have a lower expense ratio than the Regular plan of the same fund, and the gap compounds over a long goal. Compare the Direct and Regular plans before you invest.
- Consistency. Check 3- and 5-year returns, and whether performance has been steady rather than driven by one year.
- Mandate. Match the category to the job: equity for the early years, debt for the final ones.
- Manager tenure. A long-serving fund manager means the track record belongs to the person still running the fund.
Tax on gains and withdrawals
Tax applies to the gain in each redemption, not to the amount invested. For equity-oriented funds, long-term gains on units sold on or after 23 July 2024 are taxed at 12.5% above ₹1.25 lakh a financial year, plus surcharge and cess. Short-term gains on equity funds are taxed at 20%. Debt fund units bought on or after 1 April 2023 are taxed at your slab rate, whatever the holding period. These rules are as of October 2026.
Withdrawing money for fees
When you withdraw for fees, units are redeemed first in, first out, so the oldest instalments go first. Only recent instalments may still be inside an exit-load period, and exit loads vary by scheme. Plan withdrawals a little ahead of the due date, so you are not forced to sell during a fall.
Frequently asked questions
How much SIP is needed for a child's college fund?
The answer depends on the cost you assume and the years left. At 8% education inflation and a 10% assumed return, a 15-year goal starting from ₹20 lakh today needs ₹15,797 a month. At a 12% assumed return, the same goal needs ₹13,330 a month. These are illustrative figures at assumed returns.
Can I still invest in a children's scheme after the SEBI change?
New children's solution-oriented schemes cannot be launched, and existing ones stopped taking fresh subscriptions from 26 February 2026. They are to be merged into schemes with a similar asset allocation. Plan the goal with other fund categories instead, using the SIP and debt-shift steps in this guide, and check how any scheme you hold is being handled.
When should money move from equity to debt for education?
This guide's example shifts over the last three years of a 15-year goal. Moving earlier or later changes the result. A longer shift lowers the chance of a fall near the due date but raises the monthly SIP, because debt returns are assumed to be lower in this example.
Disclaimer
This article reflects the author's views as of 19 November 2026. Past performance does not indicate future returns. Examples that use assumed returns are for illustration only and are not projections. Consider your own goals and risk profile before investing.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.
The securities quoted are for illustration only and are not recommendatory.
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Blacklitt Technologies Private Limited · SEBI RIA INA000022428 · BSE enlistment 2491
Get the Blacklitt app
Put this guide to work on your own portfolio
Bring in your stocks and mutual funds once. Blacklitt sets them against a plan for your goals and risk, and tells you what to change and why.
Fee-only SEBI Registered Investment Adviser, INA000022428. No commission from any fund house, broker or company.
Scan with your phone camera to get the app.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.